How Much Does It Cost to Go to Space? $6.25 Billion.

May 30, 2020, marks another historic moment in American space ingenuity as astronauts resume their march into orbit aboard American technology. I wanted to know: how much does it cost to go to space in 2020?

I came to a total of $6.25 billion, all in.

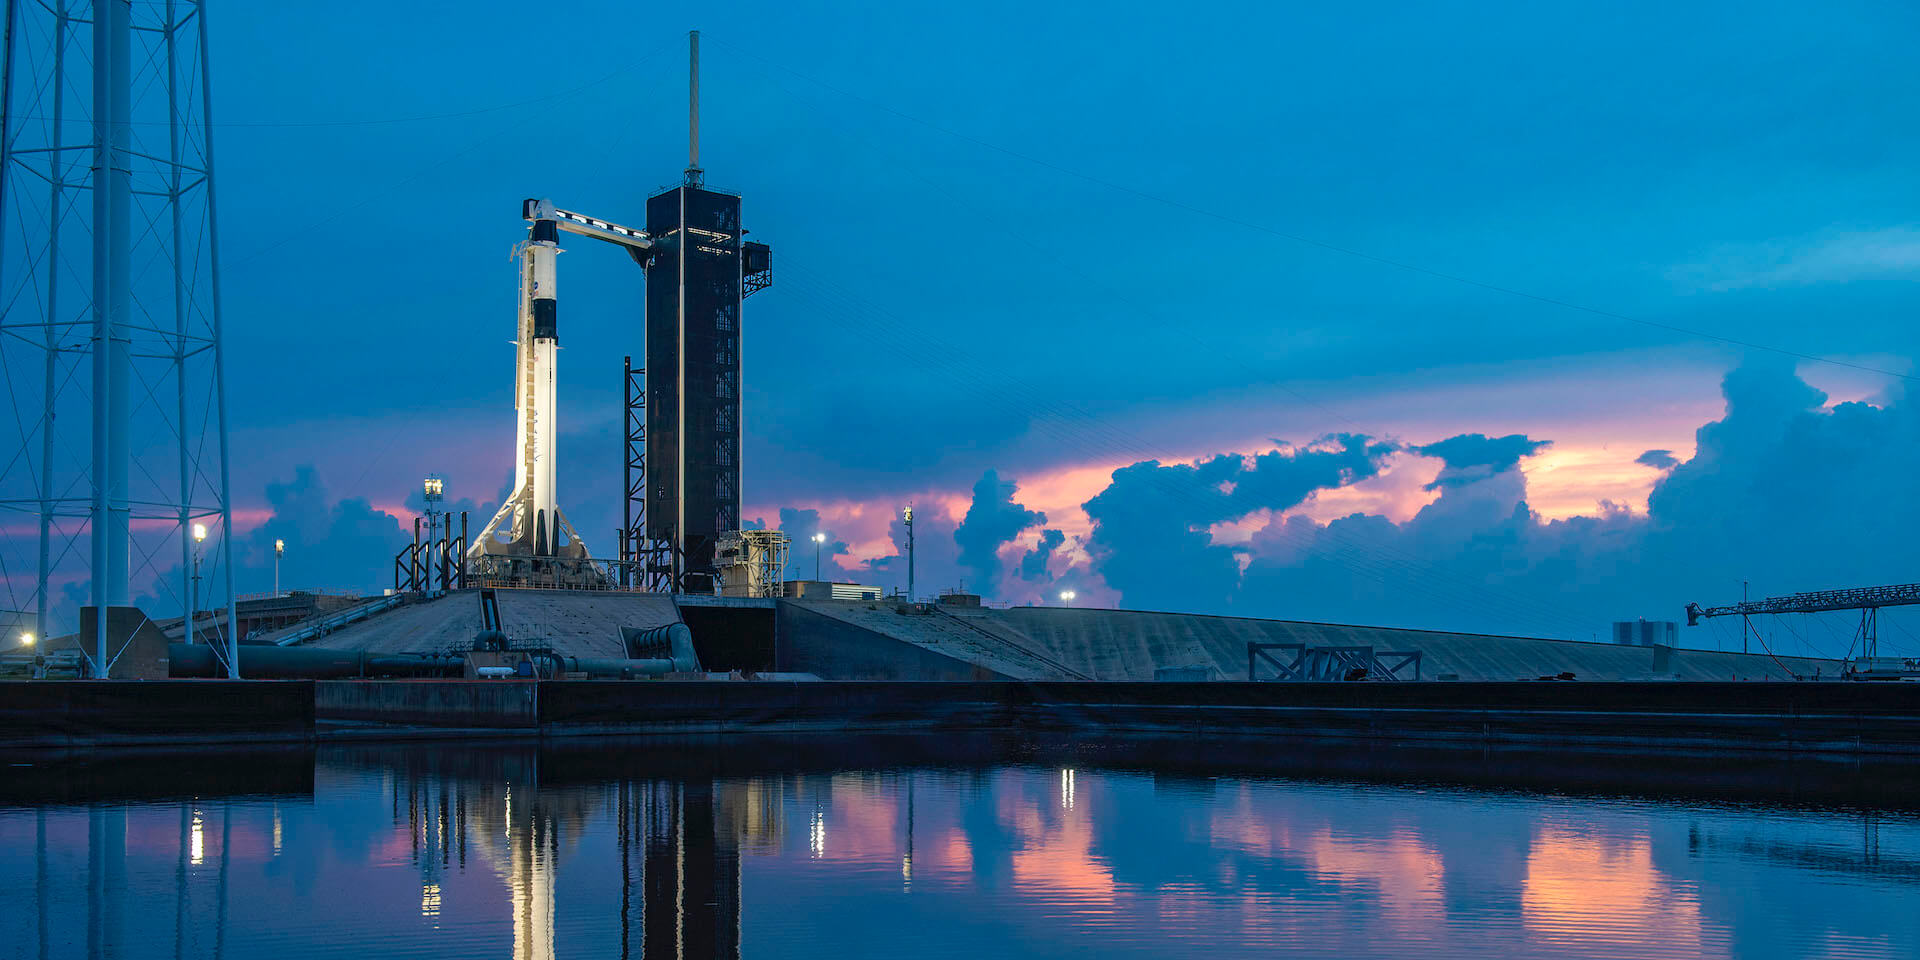
The landmark achievement rode the back of a private commercial success in SpaceX’s Dragon Capsule on Falcon rockets.

In this post, I’ll break down the total expenditures SpaceX has incurred to reach this success. While the ISS rendezvous had direct costs much smaller than $6.25B, it’s the milestone achievement that Musk has aimed for since the start.

So, what did it take to get here?

Astronauts, Made in the USA

Before I dive into the details of how much it cost to go to space once again, I’d like to review a little of what SpaceX has accomplished with NASA.

Two NASA astronauts, Douglas Hurley and Robert Behnken, recently completed their 19-hour trip to dock with the International Space Station (ISS). They’re riding in the Crew Dragon Capsule—or Dragon 2—in orbit around Earth.

The astronauts named their specific vehicle Endeavour, harkening back to the Space Shuttle they’re all too familiar with. The moment the Falcon rocket took off from Florida with its two American passengers was a milestone achievement in the Dragon concept that SpaceX started in 2005.
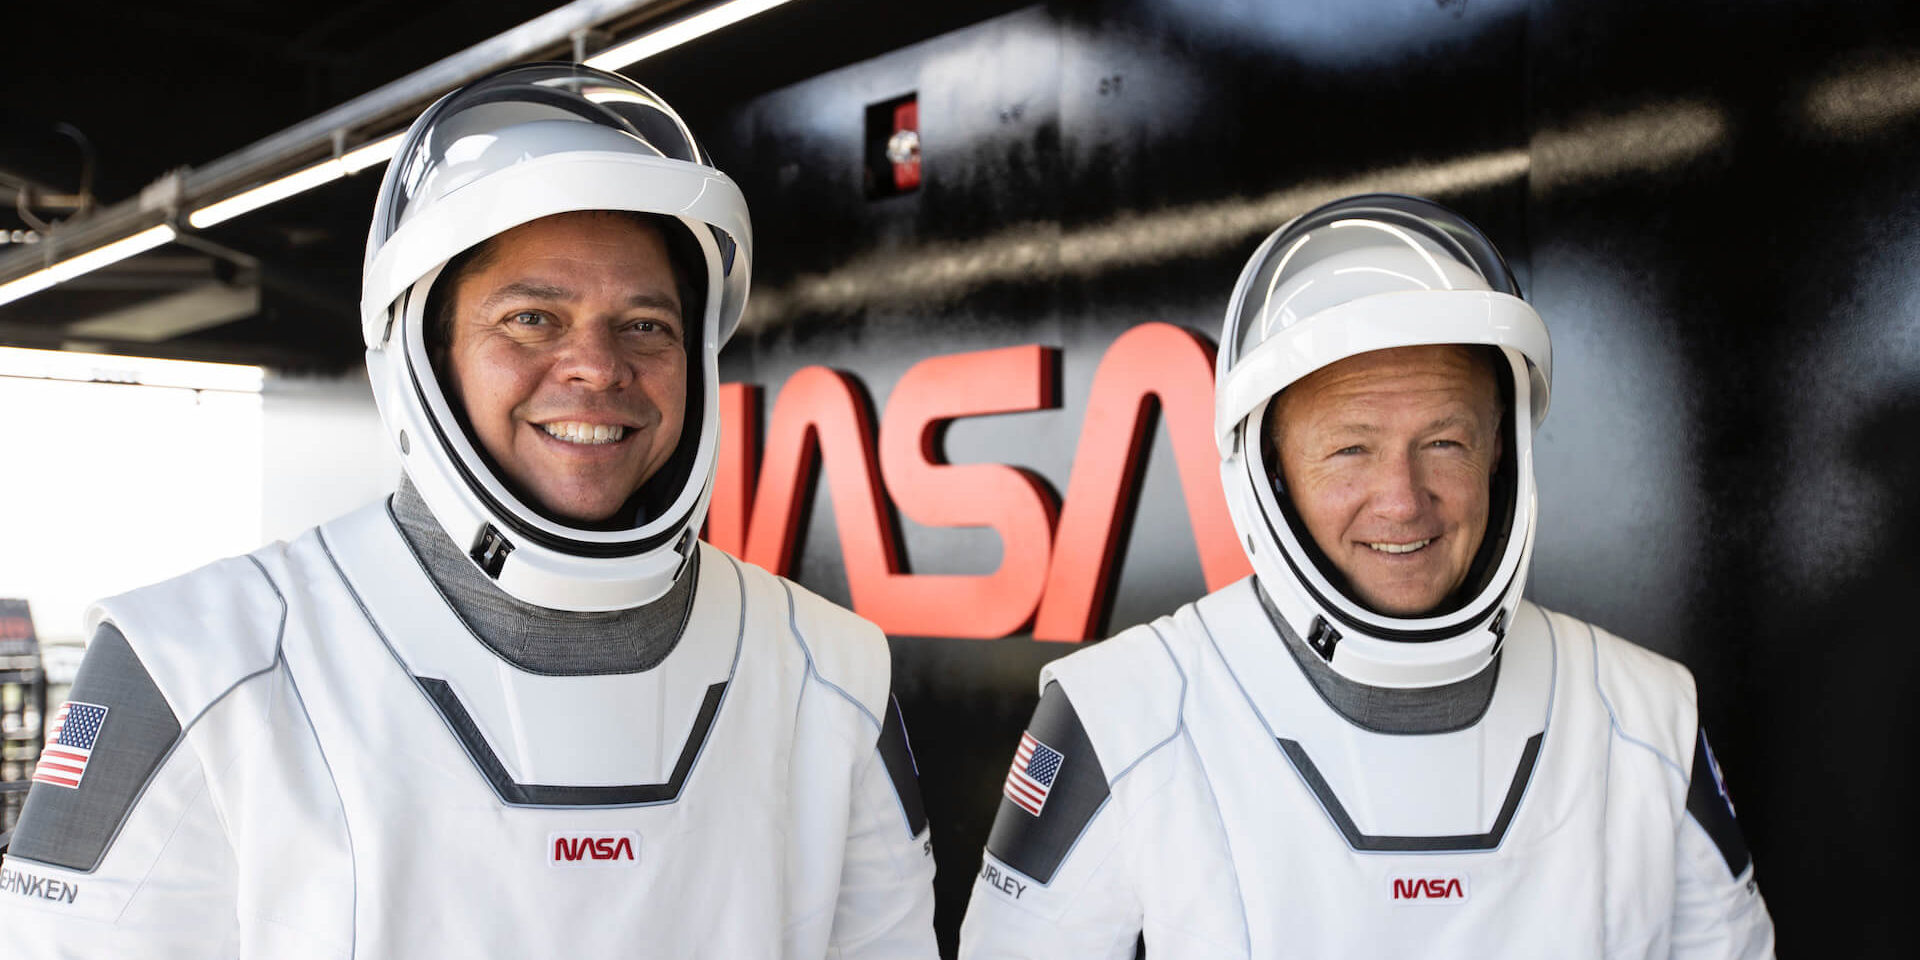
Sending Doug and Bob to the ISS via Crew Dragon.
Douglas Hurley and Robert Behnken on the way to Crew Dragon

Starting from Zero, Astronauts Reached Orbit Aboard Dragon in a Decade

The five year period after Dragon began saw significant development in Dragon’s underlying systems. Dragon’s first structural test flight was mid-2010, coinciding with the Falcon 9 rocket’s maiden voyage.

By December 2010, an operational test flight was launched with Dragon riding Falcon 9’s second flight.

In 2011, NASA began searching for private enterprise to continue missions to the ISS. NASA’s Space Shuttle program ceased in July 2011 with its last mission to the ISS for cargo delivery.

Not even two years after its initial operational test flight, Dragon saw its first goods transportation mission success as it docked with the ISS in 2012. Between then and now, Dragon has had many successful resupply missions to the ISS. Each time, the team behind Dragon learned a bit more about the capsule and how to further its mission to eventually carry humans to space again. All the while, this private commercial company fulfilled its resupply missions to the ISS, funding the human component too.

By early 2019, SpaceX began testing the Crew Dragon spacecraft, a variant of the Dragon 2 capsule. As opposed to the Cargo Dragon, the Crew Dragon capsule was designed to carry astronauts. This is the variant that would, today, carry both American astronauts into space. Technically, Endeavour is the fifth Crew Dragon, though the second to space. The first Crew Dragon to space made a similar mission to today’s landmark ISS docking, but without any crew aboard.

Paying Russia to Launch Americans

Since 2011, NASA has paid Russia to send American astronauts to the ISS.

How much does it cost to go to space? Between 2011 and 2020, it was $80 million per seat aboard Russian Soyuz capsules.

Through July of 2019, NASA spent $3.9 billion on transporting 70 American or partner astronauts to and from the ISS. That’s an average of $55.7 million across the 70 seats.

How much does it cost to go to space on Dragon with SpaceX? NASA estimates that the first six missions, including today’s, will cost $55 million per seat aboard the Crew Dragon. [1]

It’s very hard to know exactly what SpaceX has spent since its inception so that we might understand the cost to take our first two American astronauts to orbit since 2011. This is because SpaceX is a private company—we don’t have public data to analyze.

With that limitation in mind, let’s take a look at the total funding and earned contracts SpaceX has received.

How Much Does It Cost to Go to Space With SpaceX?

The closest we can get to understanding the total cost of sending astronauts Douglas Hurley and Robert Behnken to orbit in this mission is to total the known funding SpaceX has received for related work. This is from outside investment funding, personal funding from Musk, and delivered contracts from NASA.

There are some issues with this approach.

For one, SpaceX does much more than send astronauts to orbit.

The company also has contracts with the US Air Force, though some have not been completed, and others are more opaque.

SpaceX’s core business has been in sending humans and cargo to orbit or the ISS, so it makes sense to focus on outside funding to further that mission as well as known NASA contracts. While their recent delivery of a network of satellites designed to provide internet at a low cost caught a lot of attention, SpaceX’s primary revenue source is contracted deliveries to orbit and the ISS.

Let’s work through the funding to get an idea of how to answer: how much does it cost to go to space?

Elon Musk’s Personal Funding of SpaceX at its Inception

Most estimates put Elon Musk’s personal investment into founding SpaceX in 2002 at about $100 million. By 2008, SpaceX accepted $20 million in outside investment.

NASA was searching for private firms to be involved with human spaceflight in 2011. Funding awards were available to private companies that could help make that future a reality.

In the second round of commercial crew development funding awards, SpaceX earned $75 million to develop an integrated launch escape system for the Dragon capsule to improve human safety.

By 2012, estimates put Musk’s personal investment total at $100 million with another $100 million from outside investment. Estimates put the first decade of operational costs at about $1 billion. The difference, about $800 million, was from revenue on long-term launch and development contracts.

NASA’s Growth as a Source of Revenue for SpaceX

In August of 2012, SpaceX won an award worth $440 million from NASA. The award was intended to provide further funding for development and testing of the Dragon 2 spacecraft, with the Crew Dragon variant providing a method to take humans to the ISS once again.

By 2015, SpaceX raised additional outside funding in the amount of $1 billion. In 2017, another $350 million in outside funding was raised.

Later, SpaceX was awarded with another $2.6 billion worth of funding to certify the Dragon capsule for crewed flight by 2017.

Across 2019, SpaceX had multiple funding rounds with a total value of $1.33 billion. Early 2020 has already seen another $250 million in outside funding.

The Cost to Send SpaceX’s Dragon Capsule to Orbit with Two Astronauts

We can total Musk’s personal investment, outside funding, and NASA’s executed contracts to get an idea of how much money has gone into SpaceX over the last 18 years.

It’ll help us answer how much it costs to go to space in context of the entire SpaceX project from a scratch start to ISS docking.

This ignores some of the other, generally minor, funding sources SpaceX has received for more discrete work like USAF propulsion development. These are the funds that have been more focused on achieving the core mission of today’s flight, sending two American astronauts to the ISS.

To be clear: these funds have provided much more than to carry our first two astronauts on a private commercial vessel to the ISS.

They also represent the expenditures necessary to complete many resupply missions and progress towards future missions not yet completed. This is merely a snapshot in time of total funding SpaceX has received prior to a successful ISS docking mission with Dragon and crew.

DateAmount (USD, Millions)Source
2002100Elon Musk, Personal Funding
200820Outside Funding
201175NASA Award
201280Outside Funding
2012440NASA Award
20151000Outside Funding
2017350Outside Funding
20172600NASA Award
20191333Outside Funding
2020250Outside Funding
6,248Total Funding

SpaceX has most of the funds related to space logistics allotted to the company since its 2002 inception to reach today’s goal.

How much does it cost to go to space from scratch (and build an entire cargo network along the way)? $6.25 billion.

That may seem expensive if viewed as a bill to send these two astronauts, but remember that it’s the entire development and infrastructure it took to reach this point.

SpaceX will continue to provide crewed service and cargo service to the ISS, and much more, into the future.

The per-seat cost will amortize over time, drastically dropping with each successful mission.

NASA’s own estimates for the first six missions of Crew Dragon ring in at $55 million per seat.

This is the discrete cost NASA estimates for the Crew Dragon service. SpaceX has been able to obfuscate much of the development cost of Crew Dragon with its successful cargo missions as so much of the underlying systems are shared.

Space and Private Commercial Efficiency

I wrote an article a few years ago with a central theme of identifying the Apollo Program cost. That article identified the total cost, inflation-adjusted to 2020, at about $194 billion. While that crushes our $6.25 billion SpaceX mission cost for today, that was also a much loftier goal: humans on the moon. But, what about the first Apollo mission with a successful trip to orbit?

While Freedom 7 was the first American mission successfully to space with Alan Shephard onboard, Apollo 7 was the first Apollo mission to space. This mission was in 1968 and NASA began appropriating funds for the Apollo Program in 1960. Through 1968, NASA appropriated $14,105,420 for the Apollo missions.

How much did it cost to go to space in 1968 for the US? About $108 billion in costs for the first Apollo mission successfully in orbit with humans aboard, inflation-adjusted to 2020. [4]

SpaceX’s mission goes far beyond the ISS and orbit, eventually onto Mars. It’s not unlike NASA’s grandiose mission beyond Apollo 7.

Congressional testimony in 2017 discussed funding related topics for SpaceX and NASA. The estimate for the total development cost of Falcon 1 and Falcon 9 rockets was $390 million. This estimate was independently verified. Prior to this development, NASA estimated it’d cost $4 billion to develop a rocket system like the Falcon 9 using their traditional methods. That’s approximately ten times SpaceX’s audited cost.

Will SpaceX be our Spacefaring Future?

As technological improvements continue to drive down the price of our phones, tablets, and computers, it does the same for rocket launch systems. SpaceX’s major innovations in rocket recovery have allowed it to drastically cut transportation costs. If estimates turn out to be accurate, NASA should reduce their per-seat cost for sending astronauts to the ISS by nearly half versus paying for Russian Soyuz seats.

There’s one other wild thing I noticed while watching today’s launch to orbit aboard SpaceX’s Dragon Capsule. The two astronauts only had one direct action button they could press: an emergency scrub button.

SpaceX has made launching humans to orbit an automated, algorithmic process controlled by computers. Let’s hope this “autopilot” to space creates safer launches and in turn, more efficient ones.

Douglas Hurley and Robert Behnken opened up new doors for humans to explore the unknown, and they’ve done so by being as separated from the process as possible.

What was the cost to send two astronauts on a SpaceX rocket to orbit again?

FOOTNOTES

  1. NASA’s Office of Inspector General, 2019 report:
    https://oig.nasa.gov/docs/IG-20-005.pdf
  2. SpaceX, “Funding”:
    via Wikipedia
  3. Elon Musk’s Best Investments:
    via Investopedia
  4. NASA Budget Appropriations:
    via NASA History
  5. Imagery sourced from SpaceX
    SpaceX creative commons Flickr
How Much Did the Apollo Program Cost (and Was It Worth It)?

Today I’m going to analyze the Apollo program budget. We’ll answer two questions. How much did Apollo cost? And was it worth it?

Apollo Program Cost

The short answer: Apollo cost roughly $25.4 billion, unadjusted. That is about $309 billion in today’s dollars.

That was the total cost to go to the Moon. It covered more than a decade of work and six successful landings. It employed some 409,000 people. Those jobs ran through NASA, through universities, and through contractors.

The rest of this post puts that number in context. I compare Apollo to other things the country has spent money on. Then I take up the harder question. What did we get for it?

Total US Federal Outlays vs. Apollo Program (1959-1972)

How big was Apollo next to everything else the country spent in those years?

NASA Apollo Program Budget

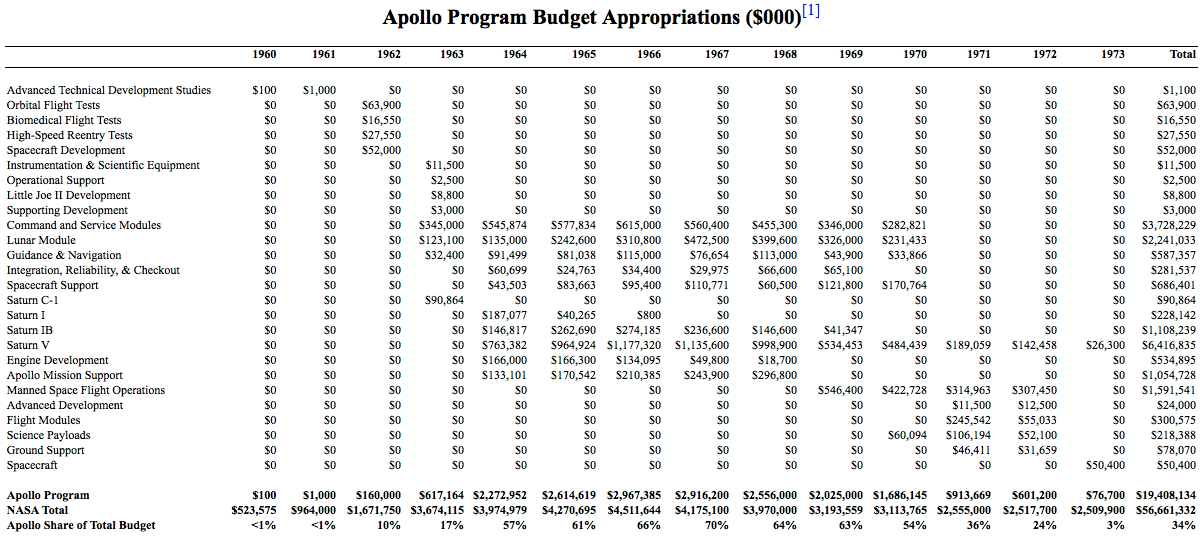
NASA’s total budget from 1960 to 1973 was $56.6 billion. Those are the years with budget lines specific to Apollo. Apollo took $19.4 billion of that. That is 34% of NASA’s spending.

But that $19.4 billion is not the whole story. It counts only research and development, and it is about $800 million short of even that. The full cost adds the tracking network, the ground facilities, and the cost of running them. Those add $5.2 billion. Put it together and you get $25.4 billion. That is the number this post uses.

NASA Official Budget Appropriations, Apollo Program
NASA’s official Budget Appropriations during and for the Apollo Program, unadjusted, 1960-1973.

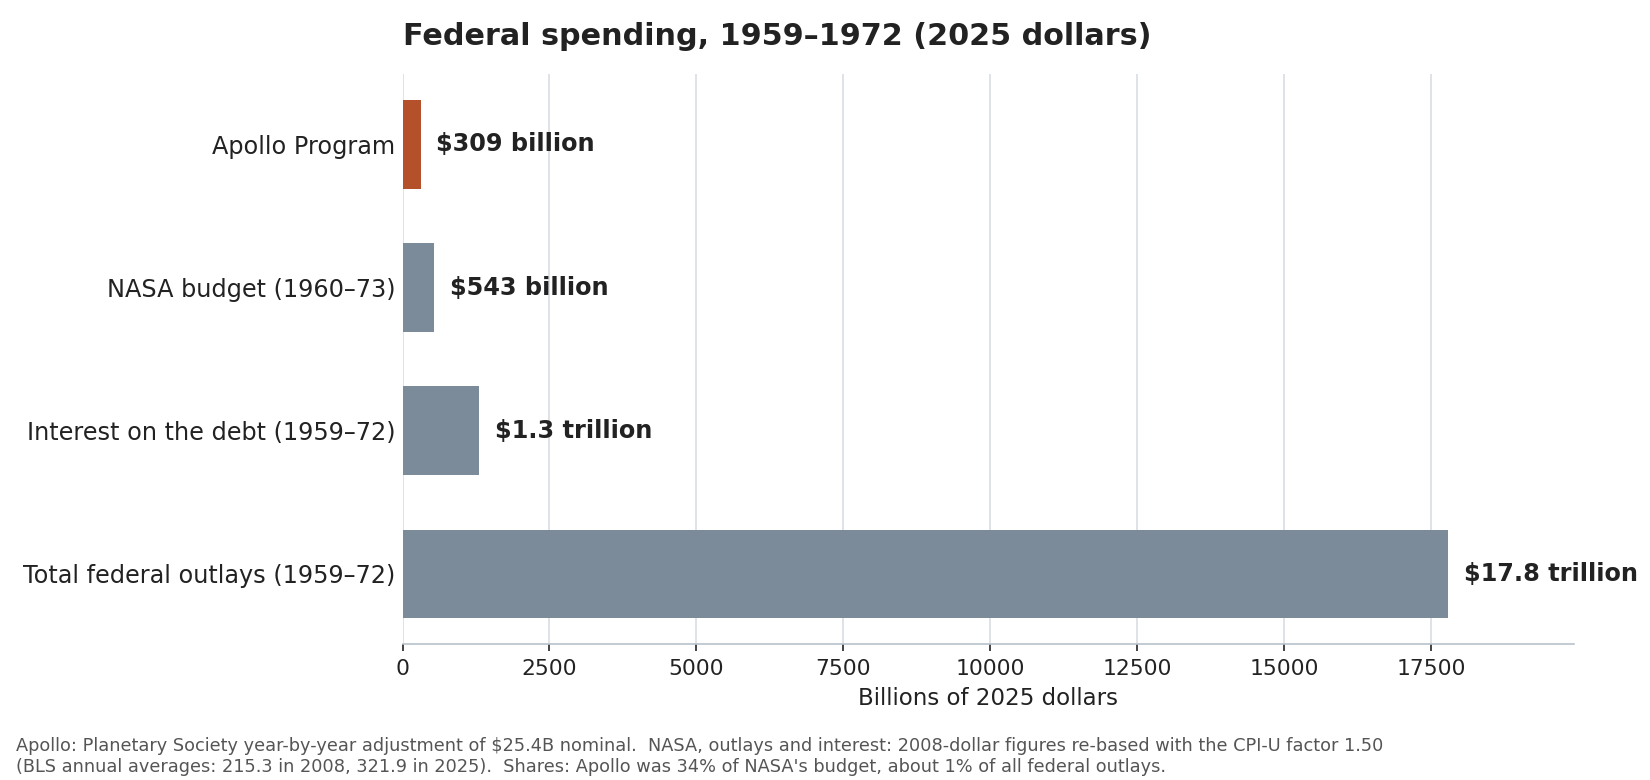
Put in 2025 dollars, NASA’s budget for the period was about $543 billion.

Federal outlays tell the bigger story. Outlays are what the country actually spent each year. From 1959 to 1972, total federal outlays were $1.9 trillion. That is about $17.8 trillion in 2025 dollars.

NASA was about 3% of that total. Apollo was a little over 1% of it.

One percent. That is the scale of the thing. The program that put people on the Moon cost about a penny of every federal dollar spent in those years.

Federal spending, 1959-1972, in 2025 dollars

Apollo Program Benefits

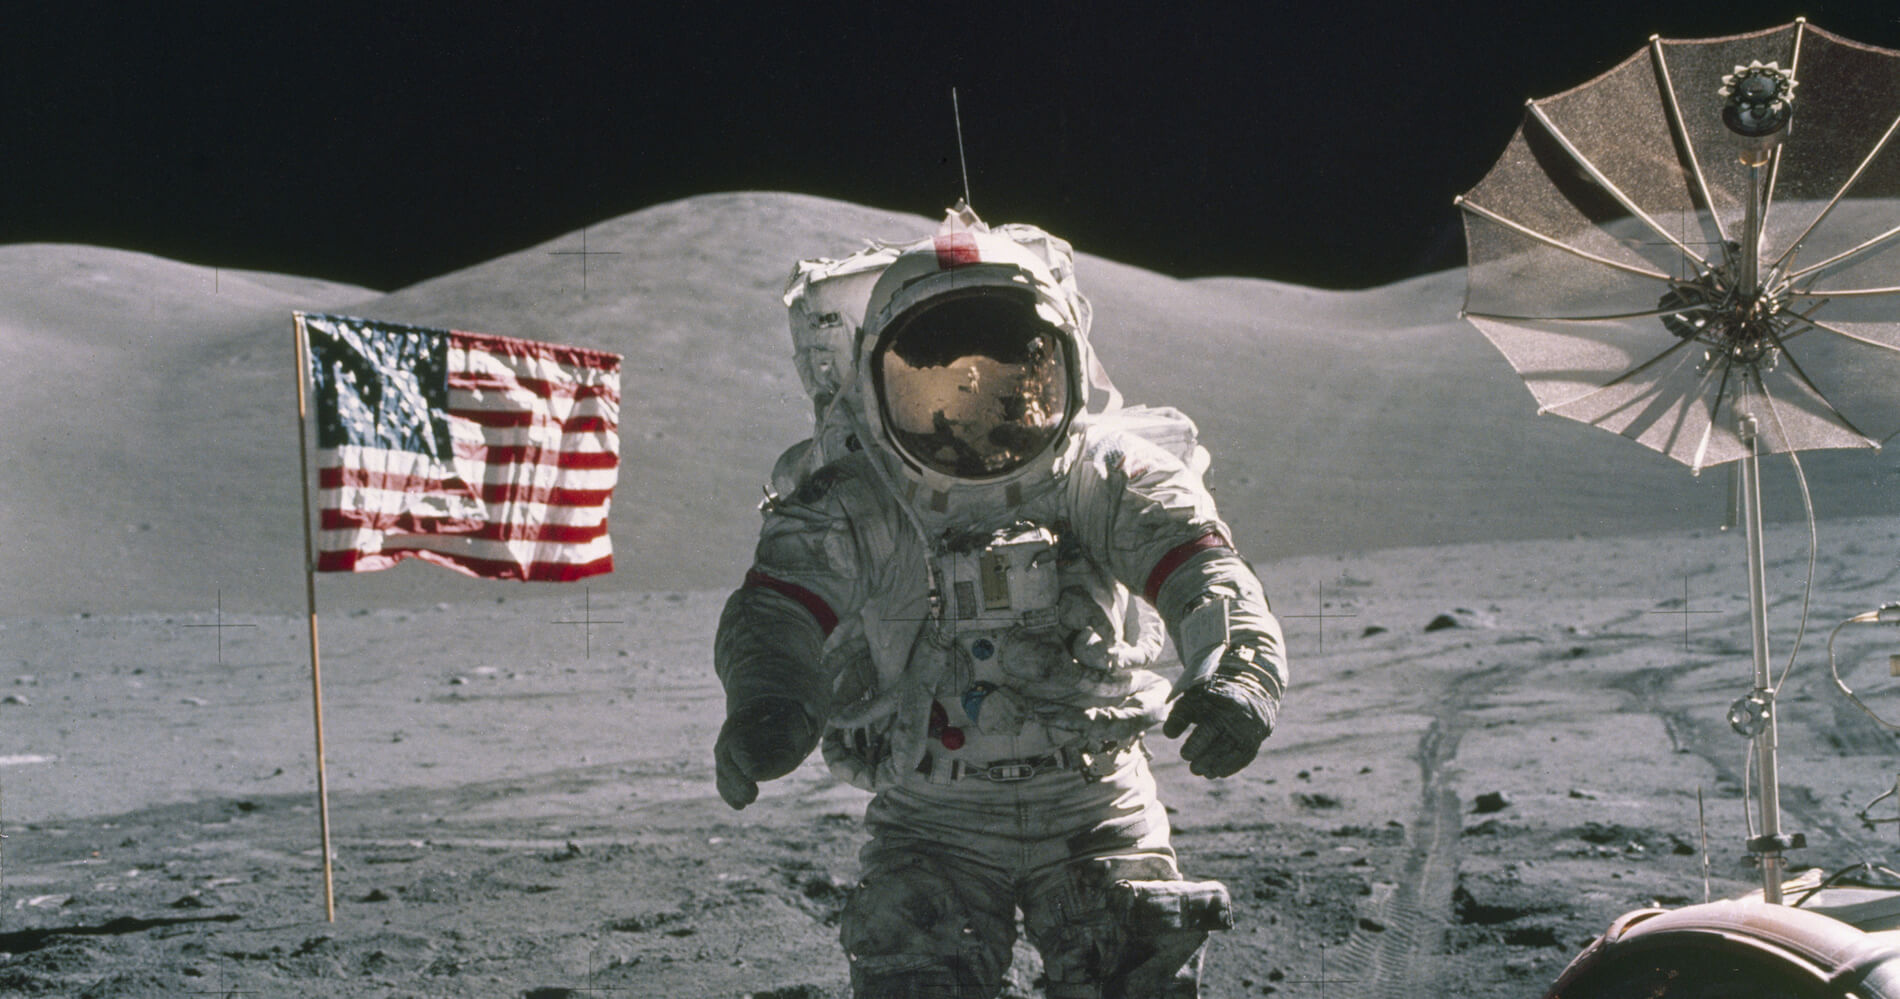
Apollo Program: Mission to the Moon

Before the comparisons, it helps to say what Apollo actually delivered. The history books cover the landings. The practical gains ran wider.

Much of the hardware from Apollo went into Skylab, America’s first space station. Skylab’s solar observatory and its experiments would not have existed without Apollo.

The 1975 docking with the Soviet Soyuz spacecraft was a step toward better relations with the USSR. It was one of the early moves that led, eventually, to the end of the Cold War.

The spinoffs reached everyday life. Here are a few:

  • Earlier detection of breast cancer
  • Faster development of integrated circuits
  • Freeze-dried foods
  • Simpler kidney dialysis
  • Insulation used in an Alaskan pipeline
  • Spacesuit textiles used in green building
  • And numerous more

Apollo cost taxpayers a significant amount of money. The benefits have been numerous. The research it sped up pushed the country to lead the 20th century in medicine, construction, and electronics.

Apollo Program vs Other Federal Projects

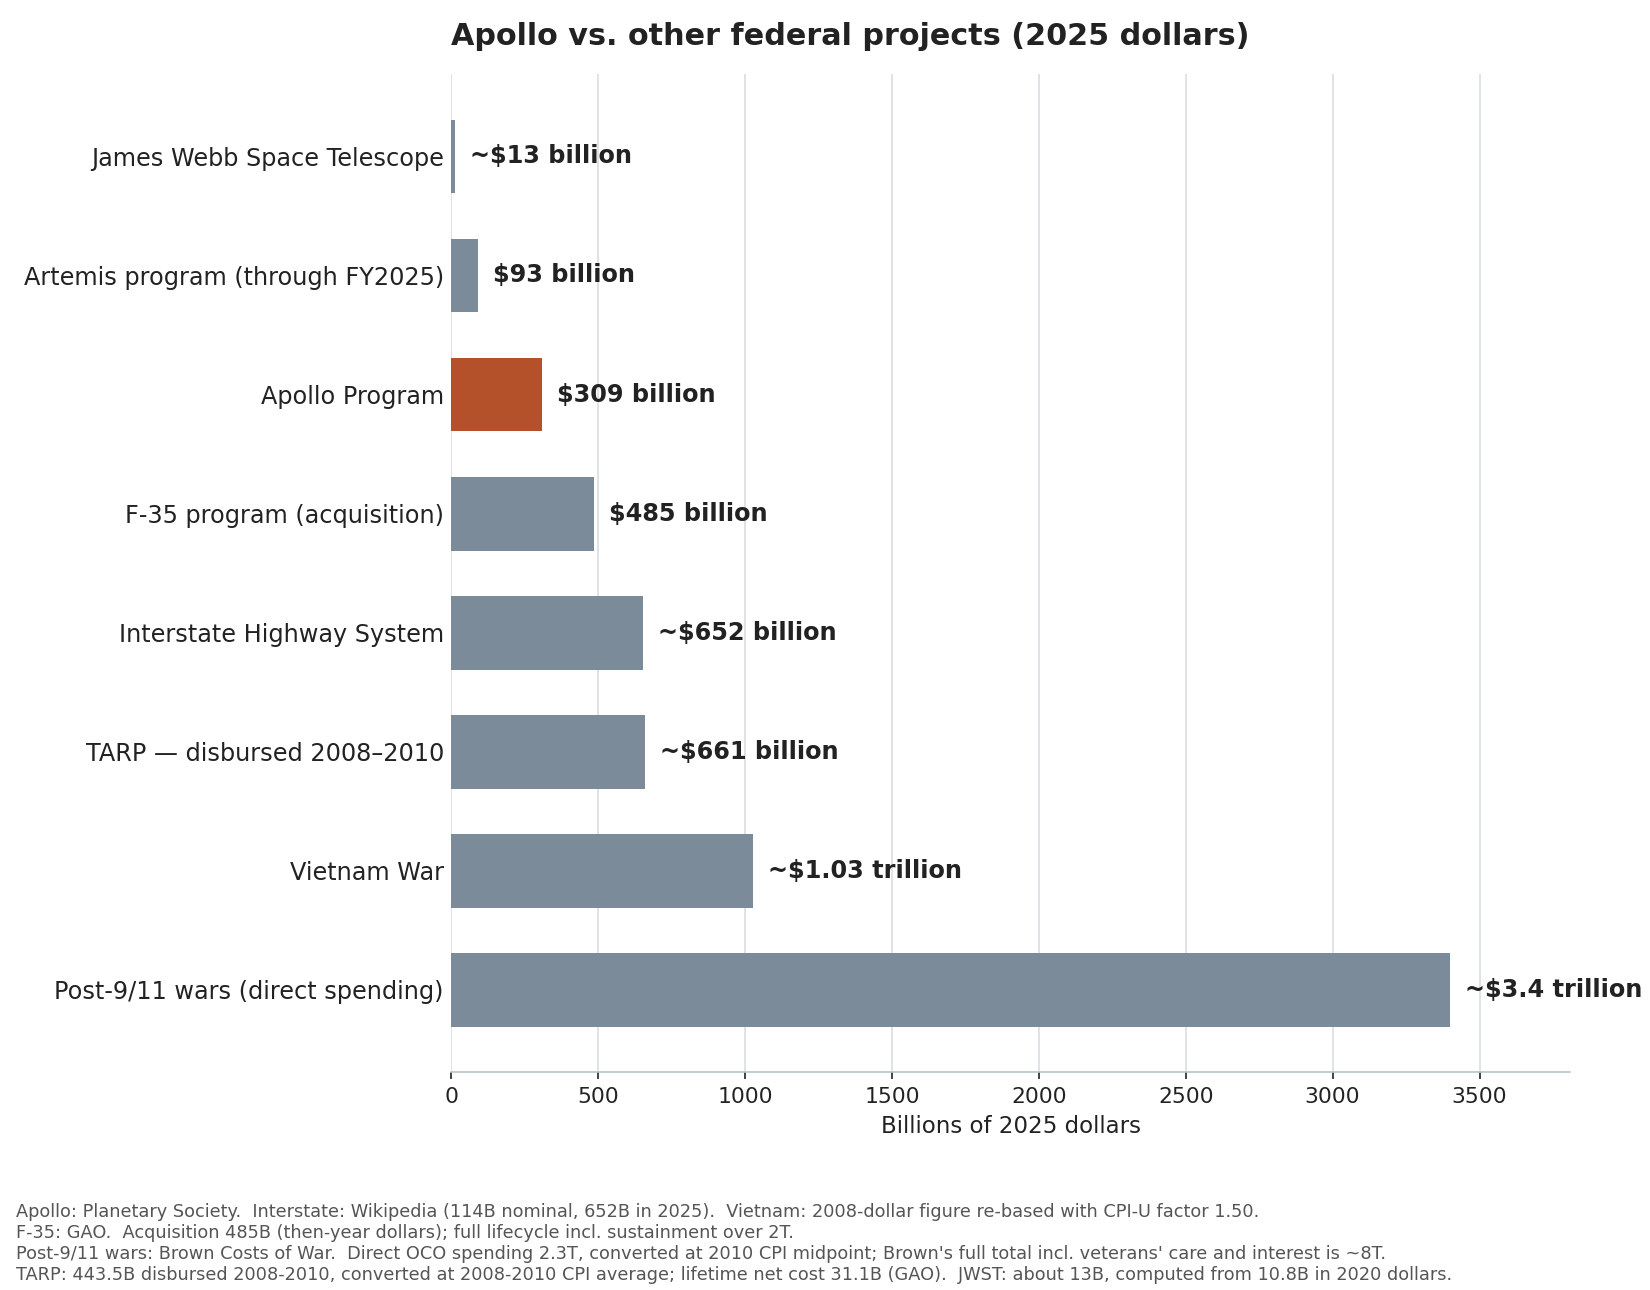
Now the comparisons. Each of these is a real thing the country spent real money on. Each is measured in the same dollars: 2025 dollars.

Apollo vs. other federal projects, in 2025 dollars

The Cost to Return to the Moon: Artemis

This is the natural comparison. Apollo went to the Moon. Artemis is going back. How do the costs compare?

NASA’s Artemis program has now flown. Artemis II carried four astronauts around the Moon in April 2026. It was the first crewed lunar flight since 1972. Artemis III is targeted for 2027. It will be a crewed test flight in Earth orbit. The first landing is now planned for Artemis IV in early 2028.

The return has not been cheap. NASA’s Inspector General projected about $93 billion in Artemis spending through fiscal 2025. In March 2026 NASA’s administrator said the public had invested over $100 billion. That is roughly a third of what Apollo cost. And no one has landed yet. Each SLS/Orion launch alone costs about $4.1 billion.

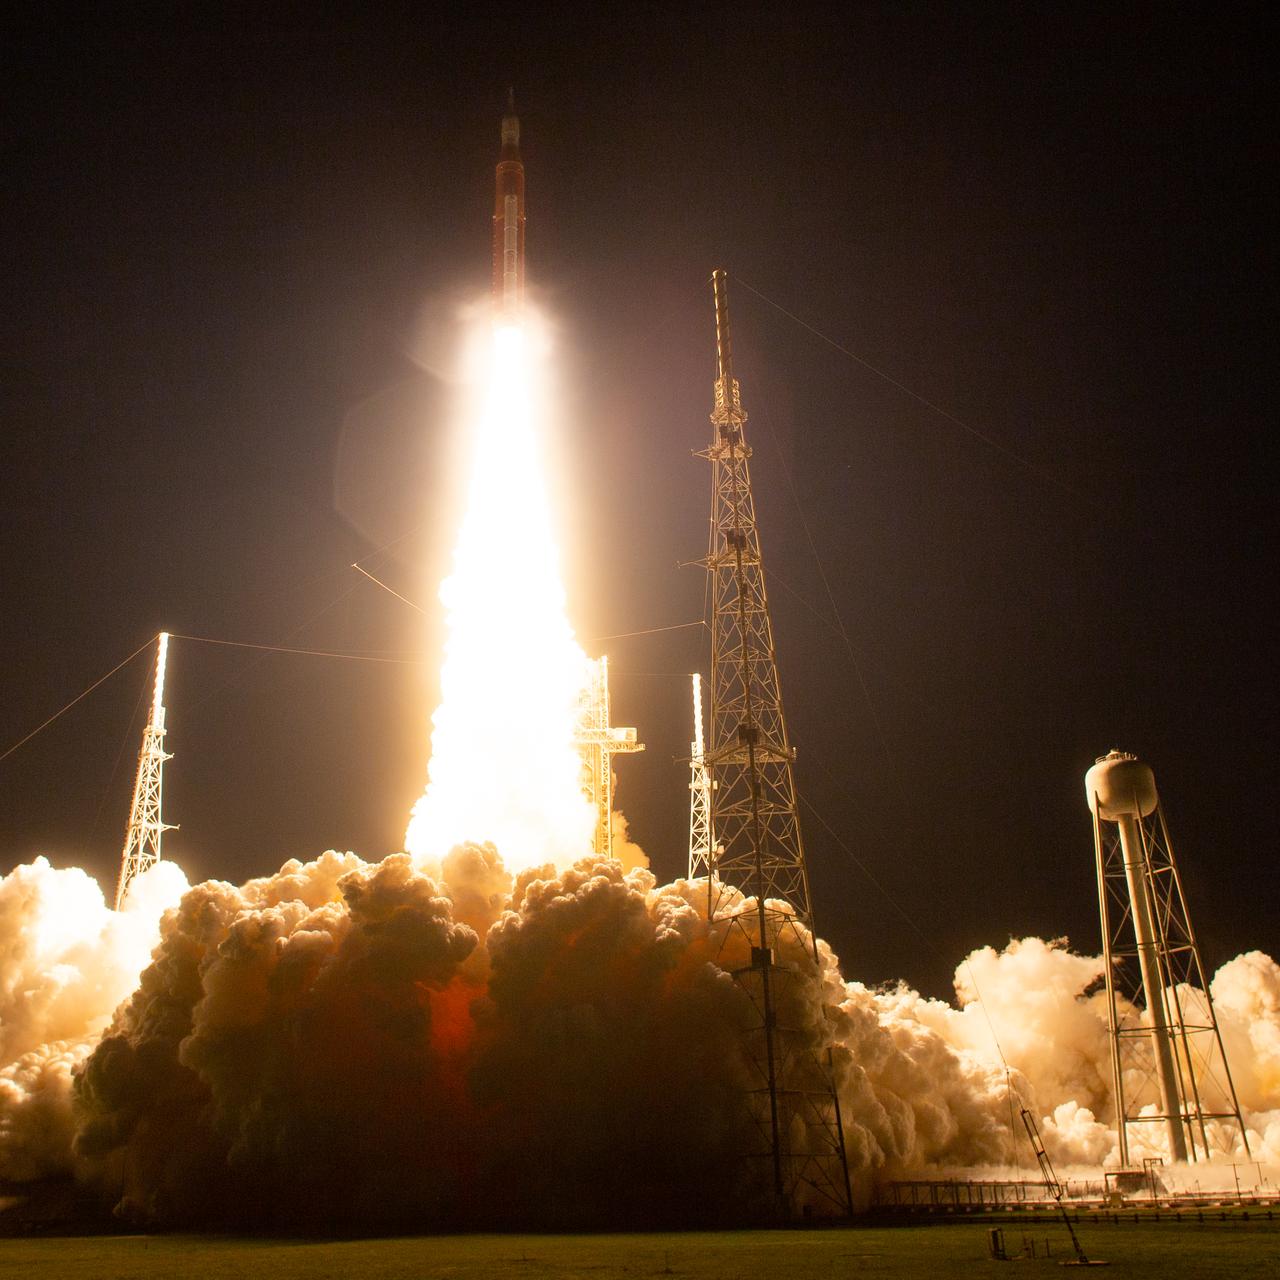
NASA's Space Launch System rocket launching Artemis I

Apollo put twelve people on the Moon for $309 billion. Artemis has spent about $93 billion and has not landed anyone. That is the honest score so far. The landing is still to come.

U.S. Interstate Highway System Cost & Benefit

The final cost of the Interstate Highway System to the federal government was $114 billion. Construction ran from 1956 to 1991. In 2025 dollars, that is about $652 billion. That is roughly twice Apollo.

Federal Interstate Highway System Cost

The Interstates gave the country tens of thousands of jobs over decades. They underpin much of the country’s economic system. Goods move across the country on them every day.

Could the country have built a more balanced system? Probably. Railroads carried America before the highways. Subsidies to highways left the rail system in a sorry state. Europe kept a mix of transport that works across long distances. The highway system was vital to how the U.S. developed. But a slightly more balanced build-out, highways alongside rail, could have left the country less car-dependent.

Vietnam War Cost & Benefit

The Vietnam War cost $111 billion from 1965 to 1975. In 2025 dollars, that is about $1.03 trillion. That is more than three Apollo programs.

It is hard to describe gains from Vietnam. America lost many brave souls in the conflict. More than 58,000 American service members died there. The country did gain military experience. That experience led to a more thorough victory in Desert Storm.

The war also changed the country at home. The voting age dropped from 21 to 18. The draft ended. An all-volunteer military took its place.

The F-35 Program

The F-22’s story is closed. Production ended in 2011, and only 187 were built. It flew its first combat missions in September 2014, over Syria. The program cost about $100 billion in 2025 dollars. That is about a third of Apollo. But the modern comparison is the F-35.

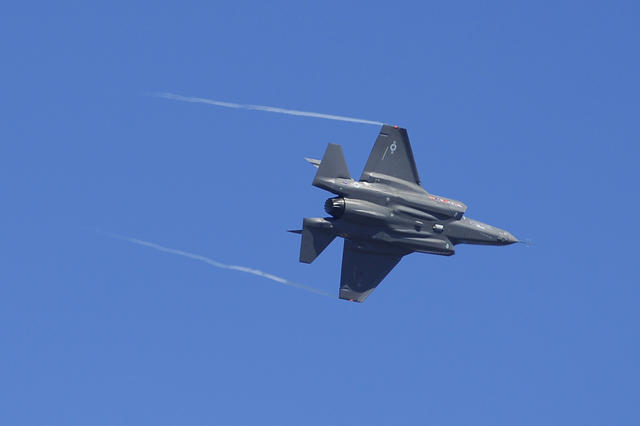
F-35 Lightning II in flight

The F-35 is the fighter the country actually bought in bulk. The Government Accountability Office puts the acquisition cost at $485 billion. That is about one and a half Apollo programs, just to buy the planes.

The full cost is larger. Sustainment will cost at least $1.58 trillion more. Together, acquisition and sustainment come to more than $2 trillion over the program’s 77-year life.

Two things to note. First, the acquisition figure is in then-year dollars, spread across decades. It is not a clean 2025-dollar number. Second, the F-35 is still being built and flown. Its final cost is not settled. Even so, the scale is clear. One fighter program costs more to buy than one and a half Moon programs, and several times that over its life.

There is value in the U.S. keeping its technological lead. The country is far ahead in conventional arms because of constant investment. I can only hope the day comes when that is no longer the concern. Climate change, starvation, and overpopulation are the larger foes.

The James Webb Space Telescope

Here is the comparison that surprised me most. The James Webb Space Telescope is the most ambitious science instrument ever launched. NASA puts its cost at $9.7 billion. That covers development and five years of operations. In 2025 dollars, that is about $13 billion. That is about 4% of Apollo.

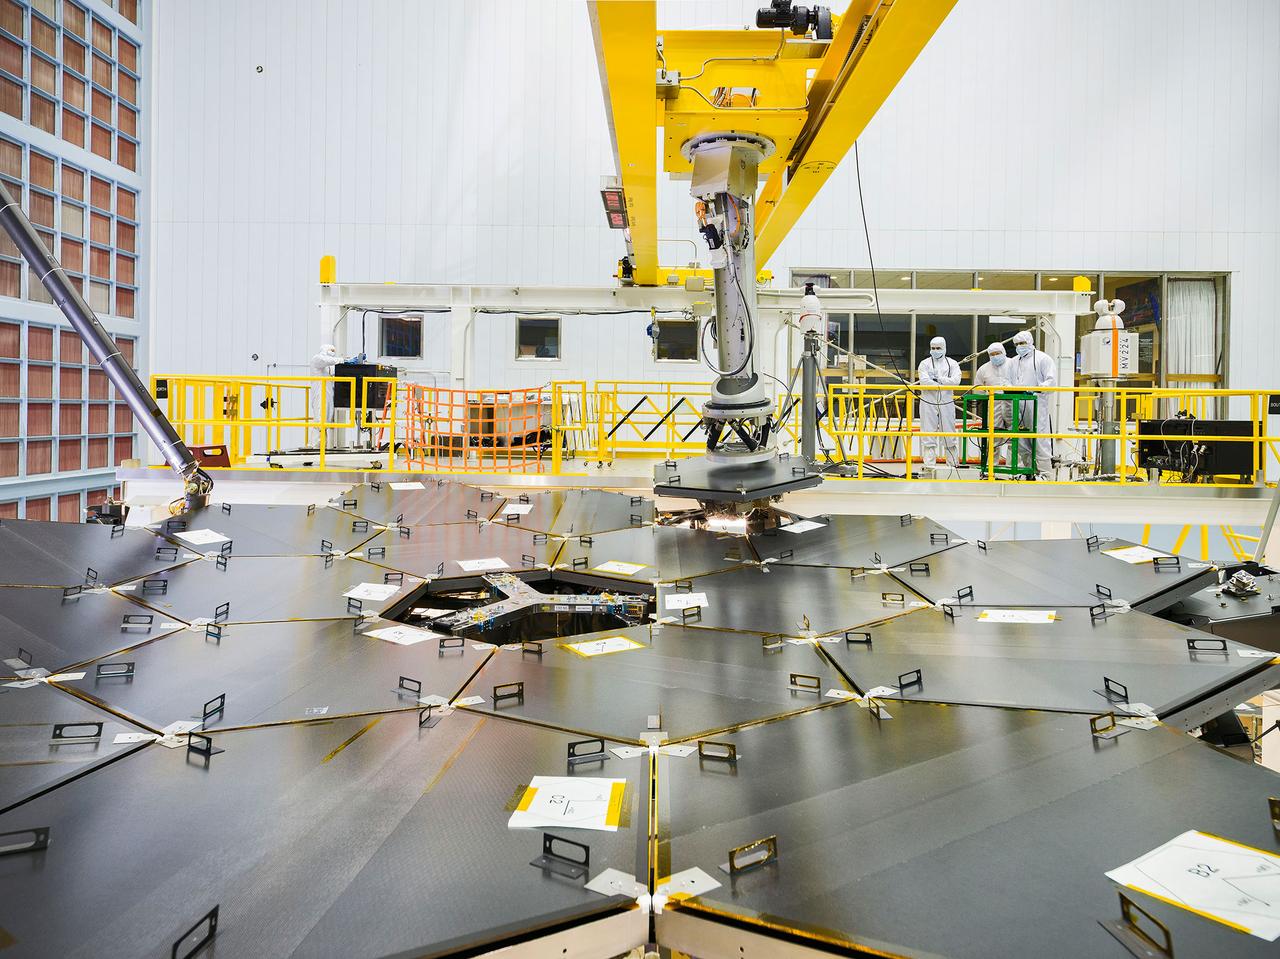
The James Webb Space Telescope primary mirror being assembled

Apollo was a program to put people on another world. Webb is a telescope. The comparison is not apples to apples. Most of Apollo’s cost was the human part: the rockets, the landers, the life support, bringing everyone home. Webb shows what a machine alone costs. Apollo shows what it costs to send people.

The 2008 Bailout: TARP

The Emergency Economic Stabilization Act of 2008 authorized the Treasury Secretary to spend up to $700 billion. The program it created was TARP. That stands for the Troubled Asset Relief Program.

TARP was not spending in the usual sense. It was investing. The government put taxpayer money into banks, automakers, and housing programs, and took assets in return. It deployed $443.5 billion. In 2025 dollars, that is about $660 billion. That is about twice the cost of Apollo.

The investments could have gone the other way. At the time, nobody knew the banks would pay the money back. In the end, they did. TARP closed in September 2023. The bank investments returned a $15.3 billion profit. The part that lost money was housing assistance and the auto bailout. The program’s lifetime net cost was $31.1 billion. Against the $700 billion authorized, that is about 4 cents on the dollar.

So the comparison cuts two ways. TARP deployed about twice what Apollo cost. But it got most of the money back. Apollo spent its money and kept the Moon landings.

Could the country have survived the Great Recession without it? We cannot rewind time and find out. Economists generally agree the Great Depression got as bad as it did because the government took a hands-off approach. This time the government took a hands-on approach. A variety of acts were passed to steady a weakening economy.

The Wars in Iraq and Afghanistan

The Congressional Budget Office estimated in 2007 that the wars in Iraq and Afghanistan would cost $2.4 trillion by 2017. That estimate is old now. The direct spending came to about $2.3 trillion. That is the Overseas Contingency Operations budget, the money spent directly on the post-9/11 wars. In 2025 dollars, that is about $3.4 trillion. It is about eleven Apollo programs.

Iraq and Afghanistan War Costs

The fuller accounting is larger. Brown University’s Costs of War project puts the total cost of the post-9/11 wars at about $8 trillion. That adds veterans’ care, interest on the borrowed money, homeland security, and increases to the Pentagon’s base budget. The $8 trillion is the full bill, not just the fighting. It is worth knowing. But the direct spending is the cleaner comparison.

The wars are over. The U.S. withdrew from Afghanistan in August 2021. It ended the Iraq combat mission that December.

The human cost is the part that matters. More than 200,000 civilians died in Iraq. About 7,000 American service members were killed across both wars. There is a grimmer number. More than 30,000 post-9/11 service members and veterans have since died by suicide.

Economically, the country gained greater access to natural resources in the region. Oil, mainly. It may have slowed radical anti-Americanism in some places. Many would argue the wars created more of it. The country is divided on whether these wars should have been fought at all. I will stick to the facts.

Interest on U.S. Debt Cost

The total interest paid on the federal debt during the Apollo years was $140.3 billion. That is about $1.3 trillion in 2025 dollars. It was more than four times the cost of Apollo itself.

And the number has only grown. In fiscal 2026 the U.S. paid $1.05 trillion in net interest on the debt. That is more than three Apollo programs in a single year.

Taxpayers are funding horrendous amounts of interest on the debt of the current generation and its ancestors. While the country needs to get its debt under control, skipping solid investments that pay dividends is foolhardy.

Was the Apollo Program Worth It?

Apollo cost about 1% of federal spending in its years. It cost less than the Interstate Highway System. Less than Vietnam. Far less than the wars in Iraq and Afghanistan. Far less than one year of interest on the debt today.

The fighter program replacing the F-22 costs about one and a half Apollos just to buy, and more than $2 trillion over its life. Artemis, the return to the Moon, has spent about a third of Apollo’s cost and has not landed anyone yet. Apollo looks cheap next to almost everything else on this list.

So was it worth it? The jobs. The technology. The pride. The hope it gave a generation. These are hard to price. But the price itself is easy to judge. Apollo was one of the cheapest great things this country has ever done.

Why are we so worried about pushing further? Any future Moon landing is a stepping-stone to Mars and beyond. The U.S. is working with private industry to make spaceflight cheaper.

Do you really believe humankind will survive on Earth forever?


Part Two, this analysis continues in:
Space Exploration Benefits and Its Future (NASA to SpaceX).


Apollo Program Cost FAQ

How much did the Apollo Program cost in today’s dollars?

The Apollo Program cost roughly $25.4 billion, unadjusted. In 2025 dollars, that is about $309 billion.

How much did Apollo 11 cost?

Apollo 11 itself cost about $355 million in 1969 dollars. That is roughly $2.5 billion in 2025 dollars. That was one mission. The whole Apollo program cost $25.4 billion unadjusted. That covers all six landings plus preparation. In 2025 dollars, that is about $309 billion.

How much did the moon landing cost?

It depends what you count. The landing itself was Apollo 11, which cost about $355 million in 1969 dollars. The program that got it there had cost far more by then: NASA’s Apollo appropriations through 1969 totaled $16.1 billion. The total cost of the Apollo Program up through about 1974 was $25.4 billion. Both amounts are unadjusted for inflation.

How much has Artemis cost so far?

About $93 billion through fiscal 2025, per NASA’s Inspector General. In March 2026 NASA’s administrator said the public had invested over $100 billion.

Types of Health Insurance Plans (Full Guide for Individuals)

Sadly, affordable individual health insurance has been a big roadblock to getting to the meat of operating a business as an entrepreneur lately. There are so many types of health insurance plans that it can be incredibly confusing to pick what’s best for yourself.

There’s a lot of options these days for individual health insurance plans.

At the highest level, there are generally two types of individual health insurance coverage, the PPO and the HMO. But in this guide, I’m going to work through the nitty-gritty of all the popular health insurance plans.

Types of Health Insurance Plans

There are several different types of health insurance plans and various levels of coverage.

The primary plans (HMO, PPO, POS) differ in how they require you to use the coverage or the costs which they cover.

Let’s review each of these types of health insurance plans and find the one which best fits your situation.

Health Maintenance Organization (HMO) Plan

The Health Maintenance Organization has existed since the ’70s in the US and is centered around a pre-selected network of doctors and medical services the plan participants can utilize while being covered by the HMO.

Generally, the patient has to have selected a Primary Care Physician (usually a general practitioner) who acts as a “gatekeeper” to other specialists and medical services. If, for example, the patient believed they needed to see an ear, nose, and throat specialist (an otolaryngologist) for a severe ear infection, the patient would first have to be examined and a referral given by the PCP to an otolaryngologist in the HMO’s network. Generally, coverage via an HMO is high (lower out-of-pocket costs) but strictly limited to the HMO network.

Preferred Provider Organization (PPO) Plan

The Preferred Provider Organization has become more popular in the past few decades as it offers greater flexibility to that of an HMO. The PPO designates a network that offers preferred (set, lower) rates for medical services to the PPO. This means that the doctors, specialists, hospitals, etc that exist in the network charge lower rates to the insured members of the PPO, and in exchange the network would receive the lion’s share of customers in the network.

n this, it functions quite similarly to an HMO – both offer networks of professionals that charge lower rates to members of the network, both charge a premium for access to the network rates for the member. However, PPOs do not have a PCP requirement nor do members need referrals to visit specialists.

Additionally, a PPO allows a patient to visit out-of-network medical services and still have coverage though at a significantly reduced level. This means that if you’re on vacation in Maui and pick-up a case of Shigellosis, your first call doesn’t absolutely have to be to your PCP for a referral (after all, you’re in Maui). You could visit a local doctor without worry though you may pay a bit more for the out-of-network service. Premiums are usually a bit higher for PPOs while care isn’t generally covered at quite as high of a level.

Point of Service (POS) Plan

The Point of Service option combines some of the advantages and disadvantages of both the HMO and the PPO. A POS is based on managed care (like an HMO), limiting service choices but lowering costs. An enrollee needs to utilize a PCP as a “gatekeeper” but the PCP may make recommendations for treatment outside the plan network, though with a lower coverage level. The patient may also have greater responsibility for form filings and general process management.

The Differences Between a PPO, HMO, and POS

So, a PPO offers flexibility at a bit higher cost while an HMO offers restricted, though often better coverage. A POS ends up combining the two, leveraging some advantages and disadvantages of both. It seems to me that most self-employed and entrepreneurs are going to wind up being traveling more often than their location- and employer-bound counterparts.

PPOs win in as being flexible and having a variety of choices. PPO individual health insurance plans for a healthy 27-year-old male in my region run from as low as $140/month to upwards of $400/month. If you qualify for ACA-related subsidies, the price can get below $100/month. There are dozens of plans to choose from with a variety of coverage levels. Let’s look at the most important ones.

Details of Health Insurance Plan Coverage

Copays

If you visit a GP or specialist because you’re feeling a bit ill, have a sudden rash, or any myriad of “I should probably go to the doctor” things, you’ll often end up with a copay for the visit you must pay out-of-pocket. Traditional PPOs have fairly low co-pays ($20-$40/visit) for doctors and specialists.

The co-pays do apply to your deductible generally which helps to reduce that amount. High-deductible plans (more on this later), often do not offer co-pays for routine services (though preventive services are still usually free) and you’ll need to fully cover the cost out-of-pocket.

Deductible

When you’re looking at different types of health insurance plans, the deductible amount should be a serious consideration.

It’s the amount the patient must pay before the health insurance plan will pay for services rendered (often this is waived for preventative care — things like an annual check-up or physical, blood pressure screenings, cholesterol blood tests, etc).

For example, you break your arm in Ireland while mountain biking and the hospital charge is $3,000. Your deductible is $1,000. Out of your pocket comes $1,000 to cover the deductible, then the individual health insurance company’s coverage is applied to the remaining $2,000 (though that doesn’t necessarily mean you won’t be responsible for any of the $2,000 – see Coinsurance). A deductible resets yearly.

Coinsurance

Coinsurance is the percentage the patient has to pay once the deductible is meant. In the example of a $3,000 hospital charge where the deductible was met at $1,000, if the patient has a coinsurance rate of 20%, they’ll need to cover an additional $400 while the insurance plan pays the remaining $1,600 — assuming this all falls under reasonable and expected services for the injury and is covered by the plan (but that’s a whole separate discussion).

Doing the math, you can see how out of the $3,000 bill, the insurance company only covered about 55% due to the deductible and coinsurance rate (this assumes the patient had no other medical expenses in the year that would have reduced the deductible and therein the total out-of-pocket cost for the broken arm). Fortunately if the patient decide to go skiing after their arm is all healed up and break a leg the same year, their deductible will be fully met and that $5,000 bill for the x-rays and cast will only require the 20% coinsurance on the patient’s part.

Out-of-pocket Maximum

An out-of-pocket maximum is a maximum amount the patient will be required to pay within a given year (resets annually). Often this is double the deductible (though the deductible is included). Given the above scenario of a broken arm and leg with a $2,000 out-of-pocket maximum, the patient paid $1,400 towards the broken arm services ($1,000 deductible and $400 coinsurance), so there’d be $600 left to meet the maximum.

The broken leg was another $1,000 in coinsurance at 20% of $5,000 but the out-of-pocket maximum of $2,000 would be reached with $600 more so the patient would only be responsible for $600 of the $5,000 for the broken leg. Additionally, any services within the same year will not require further payments from the patient now that both the deductible and out-of-pocket maximums were met.

What About The Affordable Care Act (ACA)/”Obamacare”?

The Affordable Care Act (ACA) altered many minimum requirements of healthcare coverage plans. It also pushes individuals to get coverage by way of a penalty if they do not have coverage (edit: no longer applicable).

The most interesting aspect is that it also creates a competitive marketplace for you to shop for individual health insurance.

While the marketplace may list certain “levels” associated with coverage plans (Bronze, Silver, Gold); they still represent an underlying type of plan. The levels just indicate a general sense of your liability and the cost of the plan. You still need to have a good grasp of the types of coverage, the risks/rewards of each, and how they’ll most benefit your lifestyle.

The marketplace for the ACA may vary from state-to-state as implementation, acceptance, or incorporation of the ACA evolves in each state. You will likely still be able to shop for plans without utilizing the healthcare marketplace in your state if you want to. As long as the plan meets the ACA requirements (and they generally should), you won’t be eligible for a penalty even if you buy the plan privately.

Overall, the ACA offers a wider breadth of choice shopping for individual health insurance plans while simultaneously mandating minimum coverage levels. Costs will rise for some enrollees and drop for others as certain mandates within the ACA affect maximum reimbursements or allowable costs.

Health Insurance Plan Coverage Aspects Summary

Now it’s important to consider there’s lots of nuance within the plan beyond these items so be sure to review them, additionally out-of-network coverage will have its own set of rules with higher deductibles, coinsurance, and so on. Fortunately the Affordable Care Act made lifetime maximums a non-issue where it used to be that the insurance company could stop paying once they met a certain dollar payment amount. Each plan will have specific entries for prescription, maternity, mental health coverages and more so be sure to review how the plan relates to specific services.

In review, the deductible is the amount you have to pay before your coverage kicks in, the coinsurance is how much you have to pay for coverage once the deductible is met, and the out-of-pocket max is the total amount you’re responsible for within a given year. That means you can quickly figure out how much your maximum cost-per-year is for medical coverage if the proverbial crap hits the fan. If your monthly premium is $200 and your in-network out-of-pocket maximum is $4,000, that’s a total potential cost of $6,400/year assuming you stay within the network and follow the rules. This means you better make sure your emergency fund is at least $4,000.

Affordable individual health insurance ideas

Picking An Affordable Health Insurance Plan

If you’re a healthy individual and read between the lines here, it might seem like you could be paying $200/month just so your annual physical is only $30 instead of $150 if you’d just paid it yourself. Hell, even if you did have a minor health problem during the year that ran $500 in doctor visits and prescriptions, none of that would be covered until you met your deductible. So why buy any particular one of the types of health insurance plans?

The obvious answer is of course that it’s for emergencies and the big expenses. When you have a major health issue that cost tens of thousands of dollars to treat the monthly fee for insurance and out-of-pocket maximum will pale in comparison and you’ll be happy to have the insurance. If you’re young and healthy, it’s simply a gamble to go on without it. What doesn’t make sense at all though is to have a high monthly premium in order to get low copays for the few times per year you might visit the doctor for routine aches and pains. You could pay a higher monthly premium for a lower deductible (and lower out-of-pocket maximum) or lower coinsurance as well and that could be a wise investment.

So how do you balance the cost of a monthly premium against the optional levels of coverage in a way that makes sense? You probably don’t want to pay through the teeth just to have low copays or a low deductible and rarely have a need to use it. You also probably don’t want to pay $52/month and have to shell out $15,000 when a real emergency happens, all the while having crap coverage for routine service (yes, that’s a real plan option for me at least).

Let me introduce you to the solution:

High Deductible Health Plan (HDHP) with Health Savings Account (HSA) Eligibility

Why would you want a plan that has a high deductible? Most HDHPs come with good coverage for preventative care but require you to pay for absolutely everything else out-of-pocket up to your deductible.

Catastrophic Health Insurance

For 2015, a “high deductible” health plan qualifies if its deductible is at least $1,300 for an individual or $2,600 for a family. Additionally, an HDHP sets a limit to the maximum out-of-pocket expenses – currently $6,600 for an individual or $13,200 for a family. Often, High Deductible Health Plans are referred to as catastrophic individual health insurance since they really only kick-in for very expensive procedures or many procedure occurrences within an coverage period.

Affordable Medical Insurance

HDHPs usually are quite a bit cheaper than a similar traditional co-pay oriented PPO as the mindset is that the patient has some skin in the game for every visit so the premium should be less expensive. This means that the HDHP offers a high level of flexibility of choice of doctor/specialist and a high level of responsibility for costs.

The monthly premium of an HDHP can easily be 50% less than that of an otherwise equivalent traditional co-pay PPO. Makes sense, but wouldn’t you lose the savings getting nickeled and aimed for every little thing? Not necessarily.

First, an HDHP will cover everything once you’ve met your deductible (minus your coinsurance, and even that is only up to the out-of-pocket max). Second, a wide range of preventative care is fully covered by most HDHPs (no copays even required) which is probably what you’ll use most often. Third, and most important for a long-term looking work-independent individual like yourself, is the Health Savings Account or HSA.

Health Savings Account Rules

A Health Savings Account allows you to make contributions to a bank account for medical expenses that has tax advantages as long as you follow the rules. You might be familiar with an FSA or Flexible Savings Account — they’re very similar but an HSA allows you to roll the balance over each year and earn interest on the balance or even invest it.

Whereas with an FSA your employer owns the account, you own an HSA. It travels with you year-to-year and is only tied to the bank you opened the account with. Now, just like an FSA, an HSA only allows you to spend your balance on certain medically related services and products.

There are also contribution limits ($3,350 individual, $6,550 family for 2015) just like an FSA.

The real kicker to all of these bonuses though is that the account is tax-deductible “above the line” which means that it reduces your total taxable income for the year. This health savings account deduction will likely reward you with a large refund come tax time.

When you’re considering the various types of health insurance plans, HSA eligibility might be an important factor for you.

Let’s look at a real-world scenario and see just how the numbers work.

Saving Money with a Health Savings Account

Pulling it Together: HDHP as PPO with an HSA

Let’s say Johnny who’s a freelance copyrighter fractures his left radial head (that’s your elbow!) while horseback riding in Colorado, just a few hours from home.

He’s rushed off to the emergency room and ends up needing surgery, a cast, and repeated visits for rehabilitation over the next few months. Johnny has individual health insurance qualifying as an HDHP with a $3,000 deductible and 0% coinsurance.

The out-of-pocket max is also $3,000 (the 0% coinsurance essentially means Johnny wouldn’t pay anything beyond the deductible anyway so the individual health insurance company ends up matching the deductible and out-of-pocket max).

Johnny has been contributing to his HSA for the past year and a half with a goal to meet his deductible annually, which means his contribution was $250/month ($3,000/12 months), just under the max contribution to his HSA per year.

The only other medical expenses he had in the last year was when his doctor, during a covered physical, prescribed a generic version of Nexium for frequent heartburn he was having which he’s been paying for monthly via his HSA.

At $40/month, 6 months into the year, with a total HSA investment of  $4,500 ($250/month for 18 months), he’s spent $240 on the heartburn medication leaving him with $4,260 in his HSA and $2,760 remaining for the deductible.

The cost of his fractured elbow and recovery ended up being in excess of $10,000. Johnny’s HDHP pays everything beyond the remaining $2,760 deductible which he covers with his HSA, leaving him with $1,500 in his HSA for future expenses and 100% coverage by the HDHP for the rest of the year for any further medical expenses.

Johnny’s HDHP cost him $120/month, his $3,000 contribution to the HSA reduced his taxes by $1,000 (almost completely paying for the monthly premium) and his HSA will be earning interest and investment returns for the next few decades until he retires at 65 and can draw on his HSA for regular living expenses just like a traditional IRA.

The flexibility of a PPO, the cost-control of an HDHP, and the tax advantages plus investment options of an HSA form to a fairly compelling, though not simple, individual health insurance option.

For the long-term thinking self-employed person or entrepreneur, it can provide a great shield from excessive emergency health expenses, low monthly costs, flexible investment options, tax advantages, and options in healthcare service.

This is my favorite way to use the various types of health insurance plans.

Even if you’re a cubicle worker and your deductible is over $1,200 per year, there’s a chance your employer-sponsored plan is HSA eligible — it might be time to give human resources a call!